Asset Allocation for HNIs | How to Balance Equity, Debt and Alternatives
Ask most wealthy investors how their money is invested and you will hear a list of products: a few mutual funds, some stocks, a flat or two, a fixed deposit, perhaps an AIF a friend recommended. Ask how much risk the whole portfolio carries and the answer goes quiet. That gap is where asset allocation lives, and it is the most important decision in HNI investment planning.
"Asset allocation decides how much risk you take. Product selection decides how well you are paid for taking it."
Why Asset Allocation Matters More Than Stock Picking
• It drives most of your return variability. Classic studies of institutional portfolios found that the mix of asset classes explains most of the variation in a portfolio's returns over time, far more than individual security selection.
• HNIs face concentration risk. A business, a few properties, and one employer's ESOPs can quietly make up 70–90% of net worth. True portfolio diversification starts by counting these.
• Liquidity and tax matter at this scale. Big tickets, lock-ins, and high tax slabs mean the wrong mix costs real money even if returns look fine.
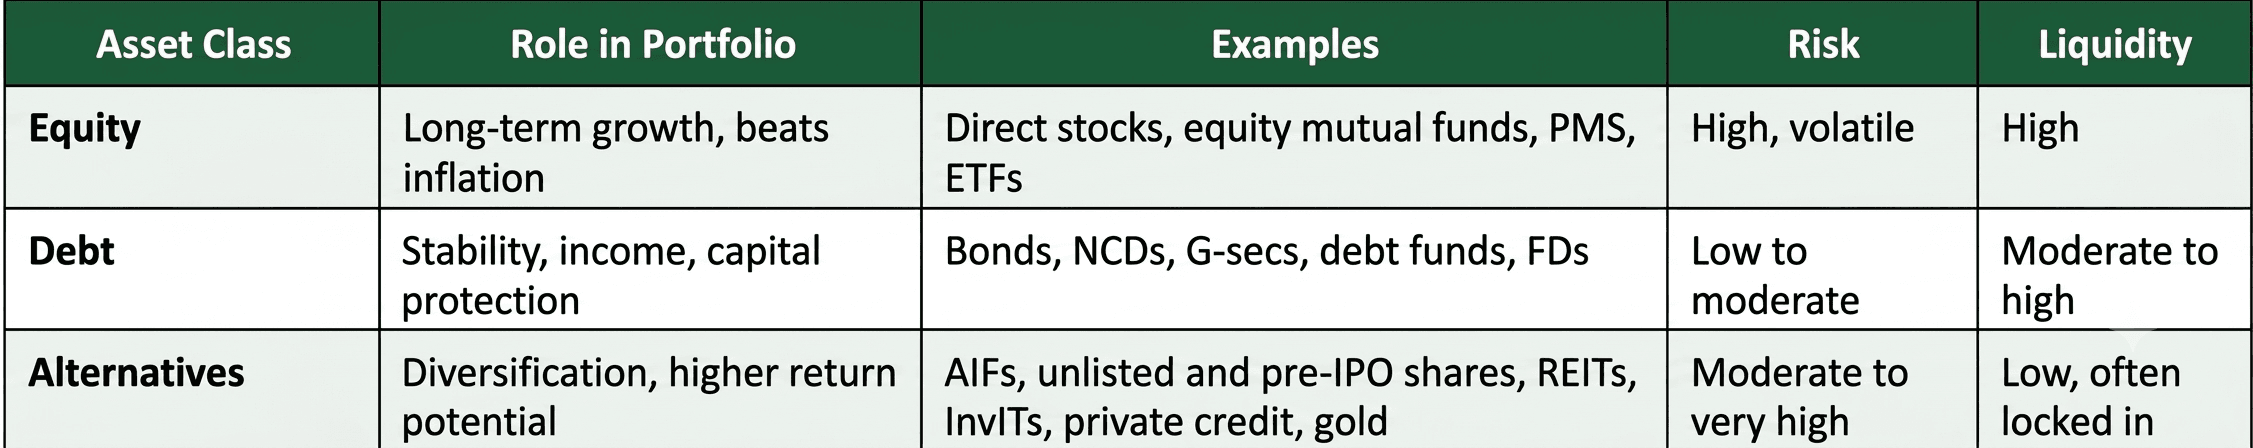
The Three Building Blocks of an Investment Portfolio Allocation
Illustrative Model Allocations by Risk Profile
Profile | Equity | Debt | Alternatives | Liquid / Gold |
Conservative | 25–35% | 45–55% | 5–10% | 5–10% |
Balanced | 40–50% | 30–35% | 10–15% | 5–10% |
Growth | 55–65% | 15–20% | 15–20% | ~5% |
Aggressive | 65–75% | 5–10% | 20–25% | 0–5% |
Illustrative ranges for discussion, not a recommendation. The right mix depends on age, goals, income stability, existing real estate and business exposure, and risk tolerance.
Asset Allocation Strategies HNIs Actually Use
• Strategic allocation: Fix target weights based on goals and risk profile, then rebalance back to them. It is simple, disciplined, and the base of most plans.
• Tactical tilts: Shift 5–10 percentage points between asset classes when valuations look stretched or cheap, while keeping the long-term framework intact.
• Core-satellite: Hold a low-cost core (index and diversified funds) for roughly 60–70% of the portfolio, and use satellites such as PMS, AIFs, and unlisted shares for higher-conviction returns.
• Goal-based buckets: Money needed in 0–3 years sits in liquid and short-term debt, 3–7 years in hybrid and debt, and 7+ years in equity and alternatives.
Worked Example: ₹10 Crore Investable Portfolio (Balanced)
Asset Class | Weight | Amount | How It Could Be Built |
Equity | 45% | ₹4.5 crore | Diversified equity funds, a PMS, and select direct stocks |
Debt | 30% | ₹3.0 crore | High-grade bonds and NCDs, debt funds, G-secs |
Alternatives | 15% | ₹1.5 crore | One Category II AIF (₹1 crore minimum) plus pre-IPO or REIT exposure |
Liquid / Gold | 10% | ₹1.0 crore | Liquid funds for emergencies, gold ETF or SGB |
Total | 100% | ₹10 crore |
|
Note the practical point: with a ₹1 crore AIF minimum, alternatives only work at this scale if you size them correctly. A smaller portfolio may start with REITs, InvITs, or gold before moving to AIFs.
Where HNI Portfolio Diversification Goes Wrong
• Ignoring real estate and business. If property and your own company are 80% of net worth, your financial portfolio is a small satellite, not the core.
• Diversifying by count, not by risk. Five large-cap funds often hold the same top stocks. More products does not mean more diversification.
• Overloading on illiquid alternatives. Cap alternatives so you never have to sell good assets at a bad time to meet cash needs.
• Never rebalancing. Winners quietly grow into oversized risks. Review yearly, or whenever an asset class drifts 5 points from target, and use fresh inflows first to limit tax.
How to Rebalance Your Asset Allocation
Method | How It Works | Best For |
Calendar-based | Review and reset to target weights once a year | Most HNIs; simple and disciplined |
Threshold-based | Rebalance whenever an asset class drifts about 5 points from target | Volatile markets; keeps risk in check |
Cash-flow based | Direct new money and maturities into underweight assets | Minimising tax and transaction costs |
• Be tax-smart: Equity gains above the annual exemption attract capital gains tax, so prefer redirecting fresh inflows or using dividends and maturities before selling.
• Revisit after life events: A business sale, inheritance, retirement, a child's education or marriage, or a large property purchase all change the right mix.
Good asset allocation is not about predicting markets. It is about building a portfolio you can hold through every market, with enough growth, stability, and diversification to meet your goals. Review it at least once a year and after every major life event.
Disclaimer: For informational purposes only. Not investment advice. Model allocations are illustrative. Investments carry market, liquidity, and capital-loss risk. Consult a SEBI-registered adviser before investing.
Build Your Asset Allocation Plan with We Grow Wealth
HNI investment planning across mutual funds, PMS, AIFs, NCDs, and unlisted/pre-IPO shares, built around your goals, liquidity, and tax position.
+91 8750563151 | www.wegrowwealth.in | info@wegrowwealth.in